Two numbers control almost everything about how your insurance actually works in practice: the premium and the deductible. Most people understand vaguely what these mean but very few understand the relationship between them well enough to make genuinely informed decisions when choosing or switching policies.
The result is that millions of people are paying for coverage that does not actually protect them in the scenarios they are most likely to face, while simultaneously overpaying for protection they will almost certainly never need. Getting this relationship right is one of the highest-return financial decisions most households can make.
This article breaks down exactly how premiums and deductibles work, how they relate to each other, how to calculate which combination makes the most financial sense for your situation, and how to avoid the traps that cost people significant money every single year.
What a Premium Actually Is
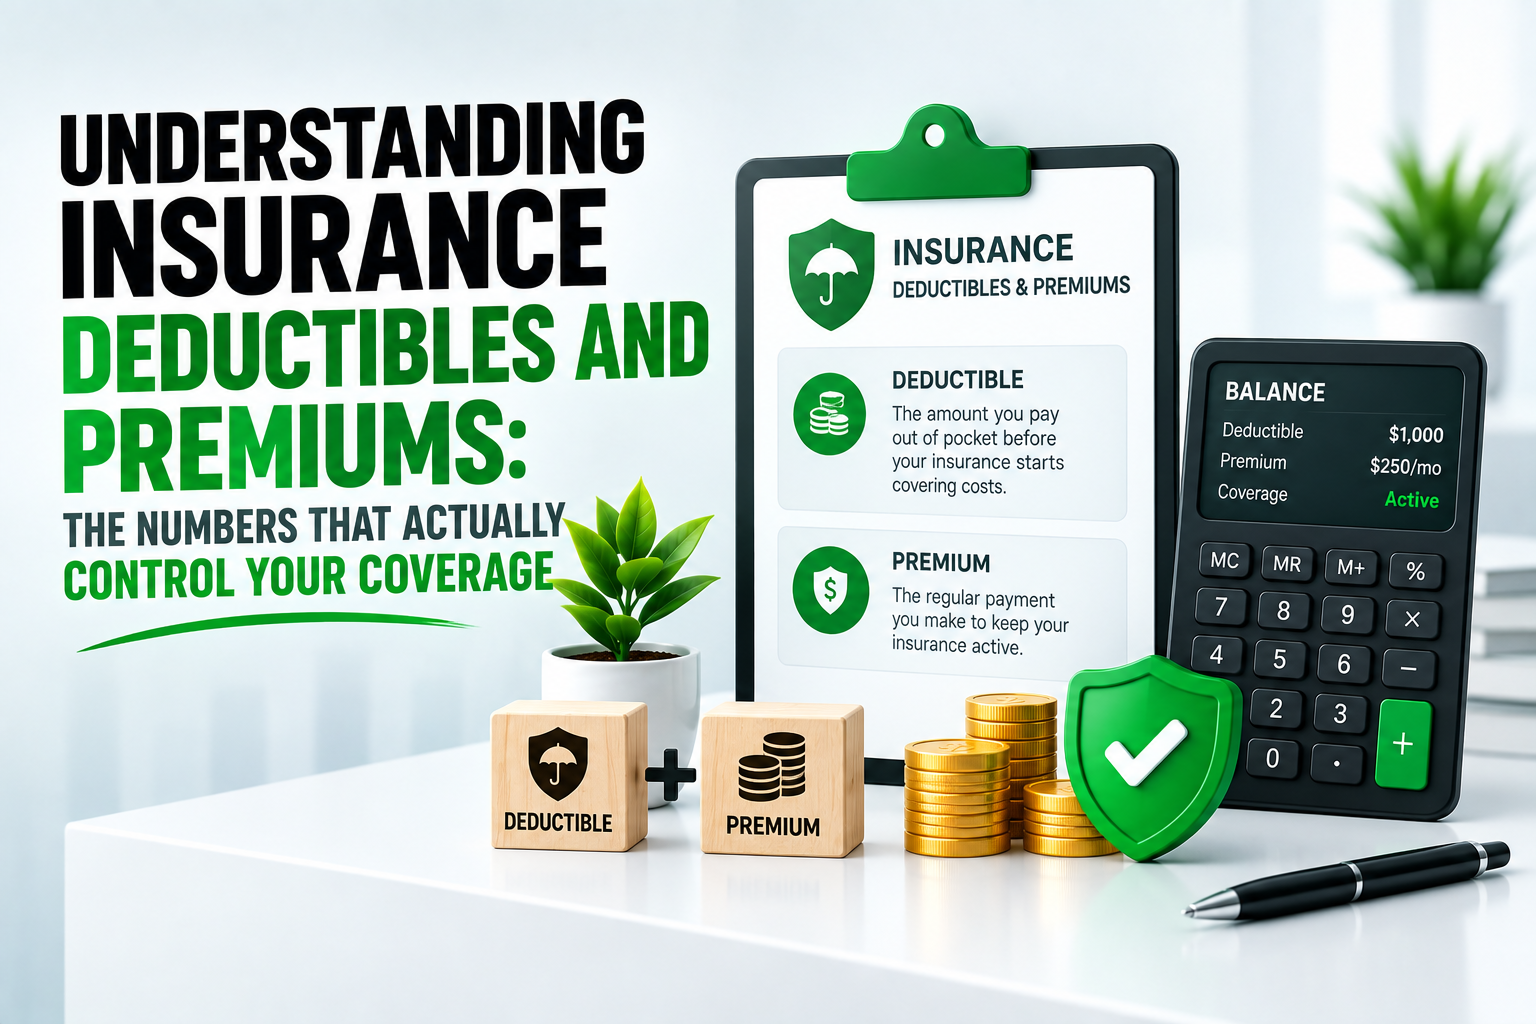
A premium is the amount you pay to maintain insurance coverage — typically monthly, quarterly, or annually — regardless of whether you ever make a claim. It is the cost of transferring risk to the insurer. Even if you go years without a single claim, the premium payments were not wasted. You were paying for the protection that existed during that period, not for claims that happened.
Premium amounts are calculated based on the insurer's assessment of how likely you are to make a claim and how expensive that claim is likely to be. Age, health status, location, claims history, the type and amount of coverage — all of these feed into the calculation. This is why two people buying the same policy can pay very different amounts.
The premium is the visible cost of insurance — the number that appears on every renewal notice and that most people focus on when comparing policies. But it is only one side of the financial equation. The other side is what you pay when you actually need the coverage.
What a Deductible Actually Is
A deductible is the amount you pay out of your own pocket before the insurance company starts covering costs. If your health insurance has a $2,000 deductible, you pay the first $2,000 of covered medical costs each year before the insurer contributes anything beyond preventive care. If your car insurance has a $500 deductible and you have a $1,800 repair, you pay $500 and the insurer covers $1,300.
The deductible serves two functions. For the insurer, it reduces the number of small claims they have to process and pay out, which keeps the overall cost of providing insurance lower. For you, it represents the threshold below which insurance provides no benefit — meaning any expense below your deductible is entirely your financial responsibility, regardless of whether it is a covered event.
The Relationship Between Premium and Deductible
Premium and deductible move in opposite directions. Higher deductible equals lower premium. Lower deductible equals higher premium. This relationship is consistent across virtually every type of insurance because it reflects a straightforward risk-sharing arrangement: the more risk you agree to absorb yourself through a higher deductible, the less the insurer charges you for taking on the remainder.
Understanding this relationship allows you to make a genuinely informed decision rather than simply picking the option with the lowest monthly cost. The question is not which option is cheaper today. The question is which option produces the better financial outcome across the range of scenarios you are actually likely to face.
| Plan Type | Monthly Premium | Deductible | Best If You... |
|---|---|---|---|
| Low deductible | Higher | $500 – $1,000 | Use healthcare regularly |
| Mid deductible | Moderate | $1,500 – $2,500 | Occasional use, some savings |
| High deductible | Lower | $3,000 – $7,000+ | Rarely need care, strong savings |
| No deductible | Highest | $0 | Chronic conditions, high usage |
How to Calculate Your Break-Even Point
The break-even calculation is the most useful practical tool for choosing between a high-deductible and low-deductible plan. It tells you exactly how many months of premium savings at the higher deductible it takes to offset the additional out-of-pocket exposure you are accepting.
Here is how it works. Suppose Plan A has a $200 monthly premium and a $1,000 deductible. Plan B has a $130 monthly premium and a $3,500 deductible. The monthly premium saving with Plan B is $70. The additional deductible exposure is $2,500. Divide $2,500 by $70 and you get approximately 36 months — meaning you would need to go three years without hitting your deductible before Plan B produces better financial outcomes. If you expect to make regular claims, Plan A is likely better. If you are young and healthy and unlikely to need significant care, Plan B probably makes more sense.
Deductibles Across Different Insurance Types
The deductible concept applies across virtually all insurance categories but works slightly differently in each context. Understanding the nuances across the types of coverage you carry prevents expensive surprises.
How Deductibles Work by Insurance Type
- → Health insurance Annual deductible resets every year. Once met, coinsurance typically kicks in — you continue paying a percentage until you reach the out-of-pocket maximum. Family plans often have both individual and family deductible thresholds.
- → Auto insurance Applies per claim, not annually. Each time you file a claim, you pay the deductible again. Higher deductibles are more appropriate for older vehicles where the repair cost relative to the vehicle value makes comprehensive coverage less valuable.
- → Home insurance Also per claim. A common mistake is choosing a very low home insurance deductible and then filing small claims — which can result in premium increases that cost more than the claims received.
- → Life insurance No deductible in the traditional sense. The full death benefit is paid to beneficiaries upon a valid claim. The equivalent concept here is the waiting period before coverage becomes active for certain conditions.
What Most People Get Wrong About High-Deductible Plans
High-deductible plans are frequently misunderstood in both directions. Some people choose them only because the premium is lower, without considering whether they have the savings to cover the deductible if they need to make a claim. This is a significant financial risk — choosing a $5,000 deductible plan when you have $800 in savings means a medium-sized medical event could push you into debt immediately.
Others avoid high-deductible plans entirely because the number looks frightening, even when the premium savings would comfortably offset the risk given their actual healthcare usage patterns and savings position. Both errors come from not doing the break-even calculation and not honestly assessing your financial cushion against the deductible.
I had been on the same low-deductible plan for six years and never once hit the deductible. When someone showed me the break-even math I realised I had been paying about $1,400 extra per year for a protection level I was never going to use. Switched plans and redirected the savings into an HSA. Much better outcome.
Rachel, 35, graphic designerThe right deductible for you is not the lowest one available or the highest one. It is the one that matches your savings cushion, your actual likelihood of making claims, and the premium difference between options. Run the break-even calculation at every renewal and at every major life or financial change. The ten minutes it takes will consistently return more value than almost any other financial decision of equal time.
Your Financial Habits
A few quick questions about how you currently manage your money.